Can you use a VA loan for Texas new construction during a 2026 PCS?
Quick Answer
Yes. VA-backed purchase loans can be used to buy or build a home, and VA says eligible buyers may buy with no down payment when the sales price is not higher than the appraised value. For Texas PCS buyers, the real issue is usually timing: the builder schedule, VA appraisal, final walkthrough, and move-in plan all need to match your report date. Texas Veterans Land Board home loans may also be worth reviewing because eligible veterans, military members, and spouses may receive up to $832,750 on fixed-rate terms, with a rate discount for veterans with a service-connected disability rating of 30% or greater. For expert updates, contact Cody Posey Real Estate.
What makes VA new construction different from buying resale in Texas?
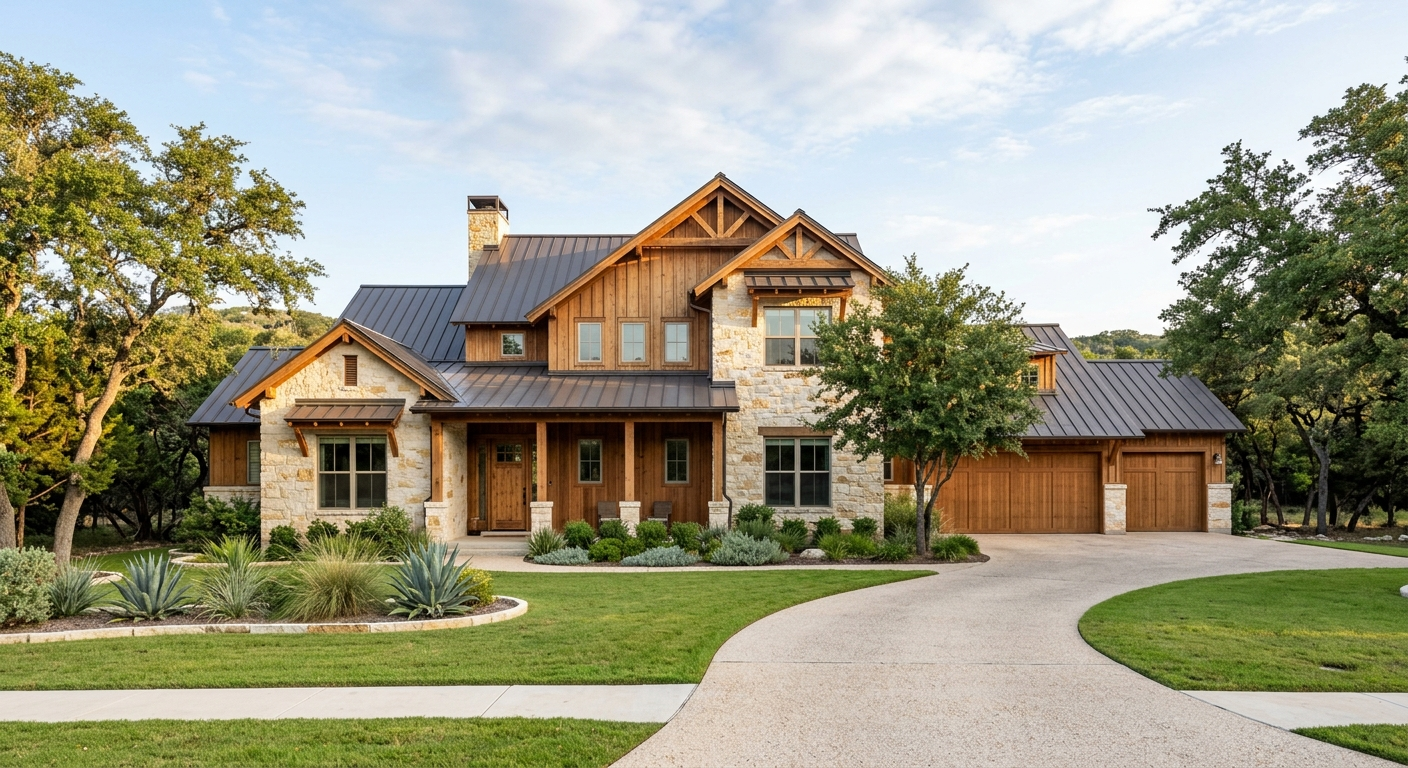
A VA loan can work on Texas new construction, but it is not the same as walking into a resale home, writing an offer, and closing thirty days later. With new construction, you are coordinating three separate tracks at once: your PCS timeline, the builder's completion timeline, and the VA lender's appraisal and underwriting timeline.
The VA purchase loan page says VA-backed purchase loans can be used to buy, build, or improve a home, and that one of the main benefits is no down payment as long as the sales price is not higher than the home's appraised value. That matters in builder communities around New Braunfels, Schertz, Cibolo, Seguin, and the broader JBSA corridor because incentives can make a new build look easy on paper, but the contract still has to survive value, condition, and timing checks.
The part I see PCS buyers underestimate is the difference between a quick move-in inventory home and a to-be-built home. A spec home that is already framed, sheetrocked, or near completion can often be planned around a PCS arrival. A dirt-start or early-stage build can be a bad fit if you need keys near a firm report date. If your orders have you landing at Randolph, Fort Sam Houston, Lackland, or Camp Bullis, the first question is not just whether you like the floor plan. It is whether the construction timeline gives your lender, appraiser, inspector, movers, and family enough room to breathe.
This is also where builder incentives need a local review. Rate buydowns, closing-cost credits, design-center credits, and inventory-home discounts can be useful, but the cleanest incentive is the one that improves your real monthly payment without creating a contract problem later. Before you sign, compare the builder offer against a normal resale path and a full VA payment estimate. If you need a refresher on the financing side, Cody's guide to VA loan inspection requirements in Texas explains how appraisal and condition questions show up before closing.
How should an out-of-state PCS buyer time the purchase?
Start by working backward from the day you need housing, not the day you want to start looking. If your report date is in September, you do not want to discover in August that the builder's estimated completion is October, the VA appraisal has not been ordered, and your household goods are already in motion.
A practical PCS timeline starts as soon as orders are firm enough to plan around. Pull your Certificate of Eligibility, talk with a VA-experienced lender, and get a true pre-approval instead of a casual payment estimate. Then decide whether you are looking at quick move-in homes, homes under construction, or resale homes as a fallback. That decision changes the whole search. Quick move-in homes are usually better for a near-term PCS. To-be-built homes can work for a future move, retirement move, or longer runway, but they are usually not ideal when the military controls your calendar.
By the 60 to 90 day window, the search should be narrow. For a JBSA-area move, that usually means comparing commute, payment, builder options, tax rate, HOA costs, and how the area fits your daily life across places like New Braunfels, Schertz, Cibolo, Seguin, Garden Ridge, and the north side of San Antonio. I would rather see a military buyer tour fewer homes with tighter criteria than burn a weekend on every model home from I-35 to Highway 46.
By the 30 to 45 day window, you want lender conditions, appraisal timing, final walkthrough expectations, and temporary lodging lined up. Remote contract signing is normal for PCS buyers, but remote decision-making should not be sloppy. The best runs happen when your agent can video walk the home, flag construction items, compare the builder's numbers to nearby resale options, and keep the lender moving before you ever cross the Texas line. Cody's VA loan Schertz PCS checklist is a useful companion if your orders point you closer to Randolph or the Schertz-Cibolo side of the market.
PCSing to the New Braunfels or JBSA area and trying to decide if a VA new build fits your report date?
Cody will map your PCS month, VA financing path, builder options, commute targets, and fallback plan before you commit to a contract.
Call Cody Posey Real Estate at 830.360.5569 · Start your VA + PCS homebuying roadmap
Which VA and Texas benefits should you stack before closing?
The VA benefit is powerful because it can reduce the cash needed to buy. VA says a purchase loan can offer no down payment, no private mortgage insurance, fewer closing costs, and no prepayment penalty for eligible buyers. That does not mean the home is automatically affordable. Your monthly number still has to absorb the loan amount, rate, taxes, insurance, HOA dues, MUD or PID assessments where they apply, and any builder-community costs.
The VA funding fee is one of the first numbers to understand. VA describes it as a one-time payment on many VA-backed or VA direct home loans that helps lower the program cost because VA loans do not require down payments or monthly mortgage insurance. For first-use purchase and construction loans with less than 5 percent down, VA's chart shows a 2.15% funding fee for Veterans, active-duty service members, and National Guard and Reserve members. VA also lists exceptions, including borrowers receiving or eligible to receive compensation for a service-connected disability.
Texas adds another layer through the Veterans Land Board. The Texas General Land Office states that eligible Texas Veterans, Military Members, and spouses may receive up to $832,750 on fixed-rate home loan terms of 15, 20, 25, or 30 years. The same VLB page says veterans with a VA service-connected disability rating of 30% or greater qualify for a discounted interest rate. That does not replace a lender conversation, but it absolutely belongs in the early payment review for a Texas PCS buyer.
After closing and occupancy, Texas homestead planning becomes part of the long-term cost picture. New construction buyers often focus so hard on base price and builder upgrades that they miss the second-year tax adjustment. In Comal and Guadalupe County, the real monthly payment conversation should include current tax rate, estimated assessed value, future homestead exemption timing, and whether the neighborhood carries extra district assessments. Cody's post on Comal County tax rate impact is worth reading before you compare builder payments side by side.
What can go wrong if the builder timeline and VA loan are not aligned?
The biggest risk is assuming the builder's estimated completion date is the same thing as your closing date. It is not. Weather, inspections, trade delays, lender conditions, appraisal timing, title work, and final punch-list items can all move the finish line. If your PCS date is fixed, a two-week delay can turn into temporary lodging, storage costs, school-calendar stress, and a rushed final walkthrough.
The VA appraisal is another common pressure point. The VA purchase loan benefit depends in part on the sales price not exceeding the appraised value when you want the no-down-payment structure. If the appraisal comes in low, you need to know what the builder contract says about renegotiation, price adjustment, buyer cash, or termination rights. This is where a polished model-home presentation can hide the real issue. The question is not whether the granite looks good. The question is what happens if value, completion, or repairs do not line up with the contract.
Minimum property and completion expectations matter too. VA-backed financing is not meant to close on an unsafe or unfinished property. On a new build, that means you need clarity around certificates, final inspections, utilities, required repairs, and any escrow holdback your lender will or will not allow. Do not wait until final walkthrough week to ask those questions.
Here is the local reality: builder reps are often helpful, but they work for the builder. For a PCS buyer, the agent's job is to pressure-test the whole plan. I want to know whether that incentive still looks good after taxes, whether the commute works when I-35 is not being polite, whether the appraisal risk is real at that price point, and whether the closing date matches the military timeline instead of just the builder's sales goal.
How to plan a VA new construction PCS purchase
- Confirm your COE, disability-status funding fee treatment, and full lender pre-approval before touring builder models.
- Separate quick move-in homes from to-be-built homes so your search matches your actual PCS window.
- Ask each builder how VA appraisal issues, completion delays, repairs, and closing-cost credits are handled in writing.
- Compare the full payment, including taxes, insurance, HOA dues, and district assessments, not just the advertised rate.
- Keep a resale-home fallback in the same commute zone in case the new construction timeline stops fitting your orders.
In Closing
If you're PCSing to the New Braunfels, Schertz, Cibolo, Seguin, or JBSA area in the next 30 to 180 days, the next step is not picking a builder first. It is building a VA timeline that matches your orders, lender, commute, and move-in deadline.
I'll help you compare new construction against resale, pressure-test builder incentives, and map the cleanest path to keys before your report date.
Ready to talk strategy? Cody Posey Real Estate at 830.360.5569.
Sources: U.S. Department of Veterans Affairs: Purchase Loan · U.S. Department of Veterans Affairs: Funding Fee and Closing Costs · Texas General Land Office: Veterans Home Loans