PCS orders in hand and thinking Schertz or Cibolo? Want to use your VA loan and still close on time?
Quick Answer
Yes, a VA loan can work very well in Schertz, Cibolo, and the northeast JBSA corridor, even on a PCS timeline. The key is to start early on the COE and lender setup so you are not trying to fix eligibility or documentation after you are under contract. One number to plan for is the VA funding fee, which ranges from 0.5% to 3.3% depending on the loan type and your situation, and some borrowers are exempt. For expert updates, contact Cody Posey Real Estate.
Why do so many JBSA buyers look at Schertz and Cibolo first?
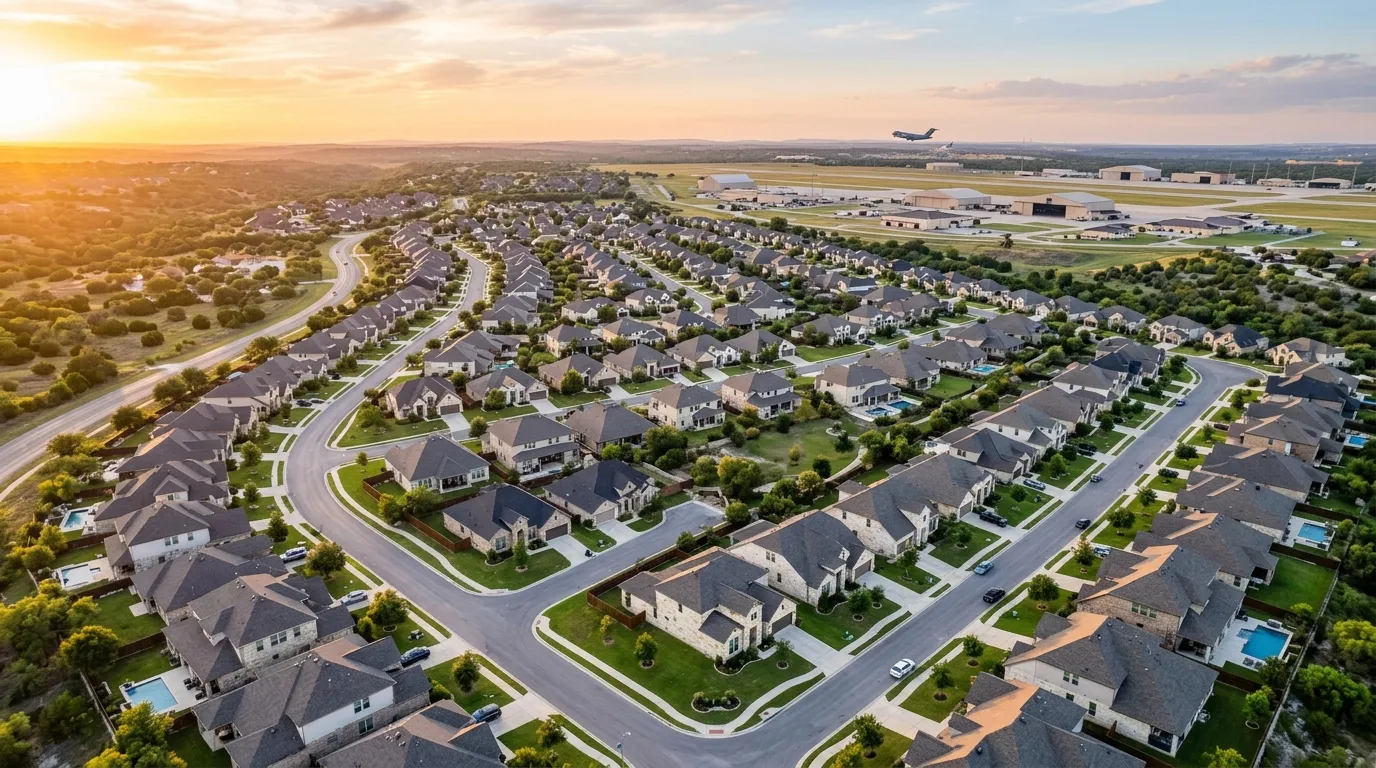
It is the corridor math. For a lot of JBSA assignments, Schertz and Cibolo sit in a spot that can make the daily drive workable to JBSA Randolph and JBSA Fort Sam, while still giving you newer housing options than many central neighborhoods.
In practice, this area gives you a mix of newer subdivisions, established neighborhoods, and a steady pipeline of new construction. That matters on a PCS timeline because you can pick the tradeoff that fits you: a resale home that can close faster, or a new-build that can line up with a reporting date if the builder timeline is real.
One Texas-specific note that surprises relocating buyers is how quickly taxes and special districts can change the monthly number. Property taxes are a big piece of the payment in this region, and some neighborhoods also have MUD or PID-style assessments. Before you fall in love with a floor plan, you want to confirm what the total monthly payment looks like with taxes and any HOA or district fees, not just principal and interest. If you want to run payment scenarios quickly, use my mortgage calculator as a starting point.
When should you start the VA loan process if you are on PCS orders?
Earlier than you think. The fastest VA closings I see are the ones where the borrower did the unglamorous setup before touring homes.
If you are about 90 to 180 days out, the goal is a clean pre-approval and a clear plan for how your housing allowance and any shift work schedules affect your shopping range. If you are 30 to 90 days out, the goal is to be fully underwritten (or as close as your lender can get) so the contract-to-close window is about the property, not your paperwork.
If you want a simple path, start with two steps: (1) pick a lender who does VA daily, and (2) get your COE handled early. The other key is to understand the Texas contract timeline so you are not surprised by the option period, inspection window, and closing steps.
PCS reality check: your timeline will feel tight even when it is not. That is why I like to build a checklist that lines up your lender milestones, your inspection window, and your appraisal timeline around your reporting date instead of hoping it all works out.
How do you get your COE without slowing down underwriting?
The COE is not the hard part, but waiting on it can be. Many buyers assume they will deal with the Certificate of Eligibility after they find a home. On a PCS timeline, that is backwards.
You can request a COE through VA.gov, and in many cases the lender can also retrieve it through the VA system as part of the loan setup. Either way, the point is to surface any eligibility or documentation friction early, not after the option period clock is ticking.
If you are missing docs or you are not sure what your status is, do not guess. Get it clarified early, then you are shopping with confidence. If you want to see the exact VA steps, here is the official COE request page: How to request a COE.
This is one of those places where a tight lender and agent team matters. I would rather spend 20 minutes this week building a clean file than lose a house next month because the file was still fuzzy when underwriting got serious.
What numbers should you know before you write an offer in Schertz?
In this market, the payment is the strategy. Before you write, you want to know three numbers: the monthly payment range you are truly comfortable with, your cash-to-close target, and your concession plan.
On the VA side, the funding fee is a one-time fee that can be financed in many cases. The VA publishes the current funding fee and closing cost guidance here: VA funding fee and closing costs. The big takeaway is that it is not a single flat number for every borrower. It varies, and some borrowers are exempt.
On the contract side, Texas uses an option period that out-of-state buyers often misread. If you have not bought in Texas before, skim this before you write: Texas option period basics.
Finally, understand how seller help actually works on VA. Not every credit is the same, and the way concessions are structured can change what the VA considers allowable versus what must be paid by the seller. If that topic is on your mind, I wrote a plain-English breakdown here: VA seller credits and the 4% rule.
Trying to line up a JBSA PCS timeline with a VA loan closing date?
I will build a VA-ready PCS roadmap, neighborhood shortlist, and offer strategy that matches your reporting date and your monthly payment comfort zone.
Call Cody Posey Real Estate at 830.360.5569 · Get your JBSA-to-Hill Country roadmap
How do VA appraisals and repairs tend to go in this corridor?
Most VA appraisals are normal, but you want to avoid preventable repair flags. The VA appraiser is not trying to fail a deal, but they do have minimum property requirements focused on safety and basic habitability.
In Schertz and Cibolo, the issues I see most often are not exotic. They are things like missing smoke detectors, peeling paint on older exteriors, roof condition questions, or straightforward safety items. In rural edges outside the core subdivisions, you can also see septic or well-related questions. That does not mean you should avoid those homes. It means you should plan for the inspection and repair conversation from day one.
If you are buying a resale home, I like to walk the property with a VA lens before we write. Not to nitpick, but to spot obvious fixes that keep underwriting smooth. If the home is borderline on condition, we talk about whether it is the right fit for a VA timeline, or whether a different property will be less stressful.
And if you are comparing new construction versus resale, remember this: a builder can fix a punch list quickly, but they can also drag out closing dates. Your best path depends on your reporting date and how much schedule risk you can tolerate.
Should you use a VA loan on new construction in Schertz or Cibolo?
Sometimes yes, but only with eyes open. New construction can look like the cleanest PCS solution, and it can be, but it introduces a different risk: the calendar.
If you go new-build, you want to confirm the builder timeline in writing, understand how incentives are structured, and make sure your lender is set up for new construction draws and change orders if they come up. I also like to confirm which fees are truly optional and which are baked into the neighborhood (HOA, special districts, and any assessment structures).
One local nuance: some newer neighborhoods in the area use additional assessments that can surprise a relocating buyer who is used to a simpler tax structure. Before you commit, ask for the full fee picture in writing so you can compare the all-in monthly payment across neighborhoods.
If you are deciding between two neighborhoods with similar prices, do not pick based only on the builder incentive. Pick based on the all-in monthly payment, the reporting-date risk, and the resale reality two to five years from now. That is the part that protects you when life changes and you need options.
What do PCS buyers usually get wrong about the Schertz corridor?
They underestimate the commute reality and overestimate how fast “close to base” feels. Here is the honest, local version: the map distance is not the drive time when you hit IH-35 or Loop 1604 at the wrong time.
This is my “only a local would say it” advice for JBSA moves. If you are leaving the house at 7:15 a.m., I want you to test that commute in the real window you will drive it. Not at noon on a Saturday. If your shift is off-peak, your world is different. The goal is not to scare you. It is to make sure the neighborhood you pick matches your actual day.
The second thing PCS buyers miss is that the cheapest list price is rarely the cheapest monthly payment. Taxes, HOA, and assessment structures can swing the payment enough to change your comfortable range. If you want a sanity check, send me the addresses you are considering and I will map the commute pattern, the tax picture, and the realistic payment range so you can compare apples to apples.
If you are torn between staying closer to San Antonio or moving into New Braunfels, I can help you compare the commute reality and the all-in payment so you pick the area that fits your day, not just your search results.
What is the simplest next step if you are 30 to 180 days from moving?
Get a VA-ready game plan, then shop with leverage. The cleanest PCS purchase is rarely the one with the most optimism. It is the one with the best plan.
Start by getting a VA-focused pre-approval and your COE process underway, then build a short list of neighborhoods that fit your reporting date, your commute window, and your payment comfort zone. From there, we can time showings, write offers with the right concessions strategy, and protect your exit options if your orders change.
If you want to talk through your specific situation, I can help you build a JBSA-to-Hill Country roadmap and a realistic offer strategy for the neighborhoods you are actually considering. For expert updates, contact Cody Posey Real Estate.
VA loan PCS checklist for Schertz buyers
- Confirm your reporting date window and any schedule constraints (shift work, leave, TDY).
- Pick a VA-experienced lender and get a fully documented pre-approval, not just a quick quote.
- Request your COE early so eligibility and documentation are settled before you write an offer.
- Run an all-in monthly payment estimate that includes taxes and HOA or assessment fees for each address you like.
- Tour homes with a VA condition lens so you avoid preventable appraisal or repair delays.
- Write the offer with a clear concessions plan and a Texas option period strategy that protects your timeline.
- Schedule inspections immediately and align appraisal timing with your contract deadlines.
- Before closing, confirm your post-closing budget (repairs, moving costs, utilities) so the first 90 days are stable.
In Closing
If you are PCSing to JBSA and planning to buy in Schertz or Cibolo in the next 30 to 180 days, the next step is not scrolling more listings. It is building a VA-ready timeline that matches your reporting date and your payment comfort zone.
I will map the commute reality, taxes and assessment notes, and the offer strategy that keeps your file clean so you can close with less stress. Call Cody Posey Real Estate at 830.360.5569, or start with the relocation guide.
Ready to talk strategy? Cody Posey Real Estate at 830.360.5569.
Sources: VA.gov — VA funding fee and closing costs · VA.gov — How to request a Certificate of Eligibility (COE) · VA Home Loan Guaranty — VA Buyer’s Guide (PDF)